The Surprising Gateway to Crypto Adoption: Why Debit Cards Might Be the Killer App
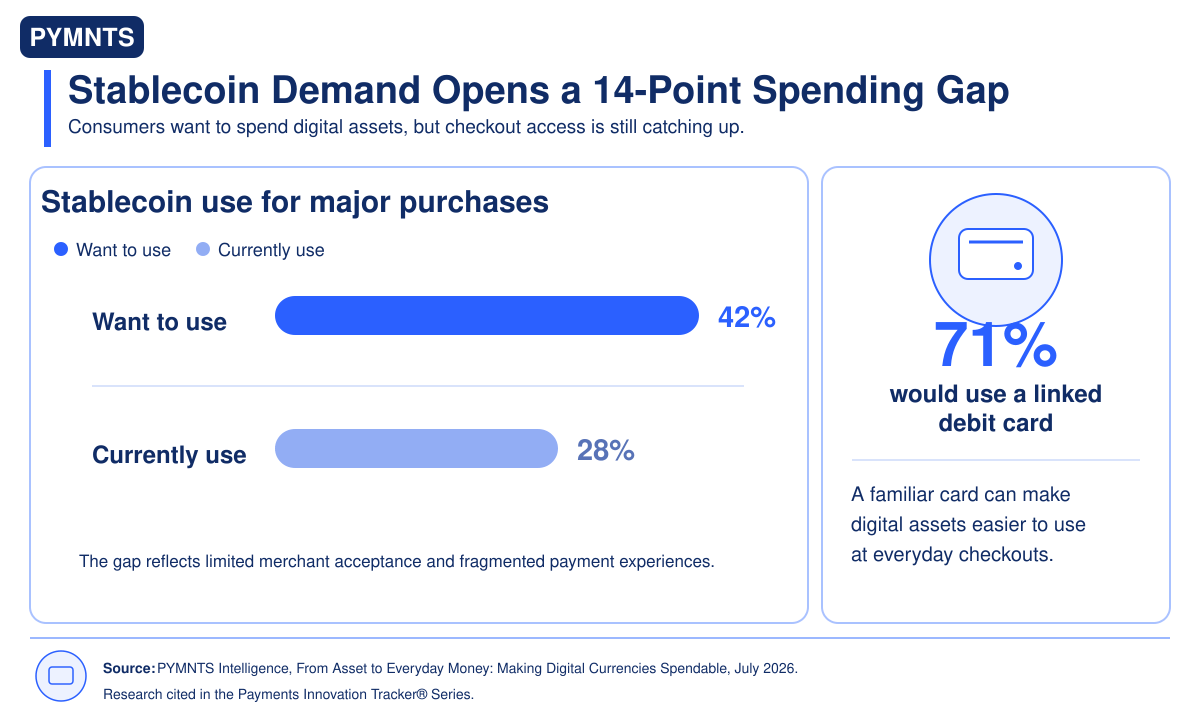
Let’s cut through the noise: cryptocurrencies have spent two decades trying to reinvent money, yet their path to mainstream adoption might hinge on a 150-year-old technology—the debit card. At first glance, this feels paradoxical. Why would a revolutionary asset class rely on such a mundane tool? But the numbers don’t lie. Seventy-one percent of stablecoin holders say they’d happily use a linked debit card to spend their digital assets. This isn’t just a statistic; it’s a revealing psychological insight into how people really want to interact with money.
The Adoption Gap: Desire vs. Reality
Here’s the crux of the issue: 42% of stablecoin holders want to use crypto for big purchases, but only 28% actually do. That 14-point gap isn’t about skepticism—it’s about infrastructure. Personally, I think this exposes a fundamental misunderstanding in the crypto community. For years, developers and investors fixated on building ever-more-complex blockchain solutions, while ordinary users simply wanted to pay for groceries without converting their assets through five different apps. The real bottleneck isn’t education; it’s convenience.
What many people don’t realize is that crypto holders aren’t asking for a radical overhaul of finance. They want familiar interfaces—banking apps they already trust, cards they can slip into their wallets, and checkout processes that don’t require a blockchain tutorial. This isn’t a failure of innovation; it’s a demand for frictionless integration.
Why Debit Cards Are Crypto’s Trojan Horse
The debit card solution is brilliant in its simplicity. By converting stablecoins at point-of-sale through existing payment networks, it sidesteps the need for merchants to adopt entirely new systems. From my perspective, this mirrors how contactless payments gained traction: no one cared whether NFC chips or QR codes powered their transactions, as long as they could tap and go.
A detail that fascinates me is how this approach commoditizes crypto itself. The underlying asset becomes just another fuel for the payment rails we already use—like how gas stations don’t care whether you pay with Visa or Mastercard, as long as the pump works. This could accelerate adoption precisely because it strips away ideological baggage. Crypto stops being a political statement and becomes a practical tool.
Trust: The Unexpected Crypto Catalyst
Seventy-seven percent of consumers would open a crypto wallet through their existing bank or FinTech app. This isn’t just about convenience—it’s about psychological safety. Humans are wired to distrust complexity, and crypto’s jargon-heavy ecosystem screams “high risk” to the average person. When I see this stat, I think about how PayPal succeeded by making online payments feel like sending an email, not wiring cash through a bank vault.
The irony here is delicious. Blockchain technology was designed to eliminate intermediaries, yet mass adoption might require leaning into trusted third parties. Banks and FinTechs aren’t just distribution channels; they’re translators between crypto’s alien logic and human intuition.
The Roadblocks Aren’t Technical—They’re Human
Yes, transaction costs and merchant acceptance remain barriers. But let’s reframe these challenges. High fees often stem from inefficient conversion layers, not blockchain limitations. Fraud concerns reflect lingering distrust in the ecosystem, not inherent flaws. What this really suggests is that crypto’s next phase isn’t about building better blockchains—it’s about designing better experiences.
Cross-border payments offer a telling precedent. Stablecoins thrive there because they solve a clear pain point: slow, expensive wire transfers. The same principle applies to consumer use. People won’t adopt crypto for its own sake, but they’ll embrace it when it quietly fixes everyday frustrations.
The Future: A World Where Crypto Disappears Into the Infrastructure
Here’s the provocative truth: For crypto to win, it might need to lose its identity. As stablecoins flow through debit cards and banking apps, they’ll increasingly feel like invisible plumbing rather than disruptive tech. This raises a deeper question: Will crypto purists accept victory if it comes disguised as assimilation?
I suspect the next decade will look less like The Matrix and more like the invention of the ATM. Digital assets will become so seamlessly embedded in our financial lives that we’ll stop noticing they’re there—until we try to imagine a world without them. And that, perhaps, is the ultimate measure of success.